
TRICARE For Life is Medicare-wraparound coverage: once you have Medicare Parts A and B, the two programs coordinate automatically, no separate TFL sign-up required. Medicare pays first for care in the United States. TRICARE For Life pays second, typically covering most or all of what’s left. The one thing you actually need to do: enroll in Medicare on time and keep your DEERS record current.
- Medicare is primary; TRICARE For Life is secondary, and coverage starts the day both Part A and Part B kick in.
- Miss your Part B enrollment window and you risk both a permanent premium penalty and a break in TRICARE eligibility.
Quick fact: TFL has no monthly premium of its own, but it requires you to pay the standard Medicare Part B premium, which is based on your income.
Key Takeaways
Medicare pays first and TRICARE For Life pays second automatically, but only if you enroll in Medicare Part A and Part B on time.
| Point | Details |
|---|---|
| TFL is automatic | No separate enrollment; coverage starts the day you have both Medicare Part A and Part B. |
| Enroll early | Sign up two months before turning 65 to avoid gaps and Part B late penalties. |
| Most claims need no action | Medicare and TRICARE coordinate payment directly for the majority of covered services. |
| Advantage and Part D are usually unnecessary | TFL and TRICARE’s pharmacy program already provide broad coverage for most retirees. |
| Overseas and VA care differ | TRICARE often becomes primary overseas, and VA billing works differently than civilian Medicare. |
| Get personalized guidance | Greenins’s certified Medicare Insurance Planners® offer free, one-on-one consultations on enrollment timing and plan decisions. |
Table of Contents
- What TRICARE For Life Covers and How It Coordinates With Medicare
- When Should You Enroll in Medicare to Keep TRICARE Active?
- How Do Claims Get Paid Between Medicare and TRICARE?
- Do You Need Medicare Advantage or Part D With TRICARE For Life?
- What Changes If You Live Overseas or Use VA Care?
- Your 7-Step Checklist Before and After Turning 65
- How Green Insurance Agency Helps You Coordinate Medicare and TRICARE
- What Retirees Consistently Get Wrong About This Transition
- Schedule a Free Medicare Consultation With Greenins
- Sources
What TRICARE For Life Covers and How It Coordinates With Medicare
TRICARE For Life is not a separate insurance plan you buy. It’s a Medicare supplement built specifically for military retirees, their eligible family members, and survivors who qualify for both Medicare and TRICARE. You don’t apply for it, and there’s no enrollment fee. The moment you’re entitled to Medicare Part A and enrolled in Part B, TFL activates.
Eligibility hinges on individual entitlement, not household status. If you’re a retiree turning 65, your coverage kicks in based on your own Medicare enrollment. Your spouse, if younger than 65, stays on TRICARE Prime or TRICARE Select until they hit their own Medicare milestone. One person’s birthday doesn’t change the other’s coverage.
Where you live matters, too. Medicare’s coverage area stops at U.S. borders and territories, which becomes important later when we talk about retirees living overseas.
Here’s the cost logic in the simplest form:
| Scenario | Who Pays |
|---|---|
| Service covered by both Medicare and TRICARE | Medicare pays its share, TRICARE covers the rest, you typically owe nothing |
| Service covered by Medicare only | Medicare pays; TRICARE doesn’t add anything |
| Service covered by TRICARE only (Medicare doesn’t cover it) | TRICARE may pay as primary |
| Service covered by neither | You’re responsible for the full cost |
There’s also a lesser-known wrinkle: if you exhaust a Medicare benefit, like the limited number of covered days in a skilled nursing facility, TFL can sometimes pick up additional coverage TRICARE would normally provide on its own. It’s not unlimited, but it’s a safety net most retirees don’t realize exists until they need it.
When Should You Enroll in Medicare to Keep TRICARE Active?
Timing determines whether this transition is smooth or stressful. TRICARE recommends enrolling in Medicare Part A and Part B at least two months before you turn 65, not on your birthday and not after. Waiting invites a gap where you have neither TRICARE Prime/Select benefits nor TFL.
Here’s the enrollment sequence that avoids problems:
- Watch for your Initial Enrollment Period, which runs from three months before your 65th birthday month to three months after.
- Sign up for both Part A and Part B, even if Part A is premium-free based on your work history.
- If you’re still working past 65 with employer coverage, ask about a Special Enrollment Period instead of the general one.
- File through the Social Security Administration’s Medicare sign-up page, online or by phone.
- Update DEERS with your Medicare number and effective dates as soon as your card arrives.
Skip Part B during your window and you’re not just risking a coverage gap. You’ll likely lose TRICARE eligibility and face a late-enrollment penalty from Medicare, added permanently to your monthly premium.
- Have your Social Security number, military ID, and marriage/birth certificates ready when you call DEERS.
- Confirm your Medicare card lists both Part A and Part B effective dates before assuming you’re covered.
How Do Claims Get Paid Between Medicare and TRICARE?
Most claims move through an automatic pipeline, and understanding the sequence helps you spot billing errors before they become headaches. Medicare processes the claim first and pays its portion directly to the provider. The claim then forwards electronically to TRICARE’s contracted processor, which pays the remaining allowable amount. In the large majority of cases, you never see a bill.
A few real-world examples make this concrete:
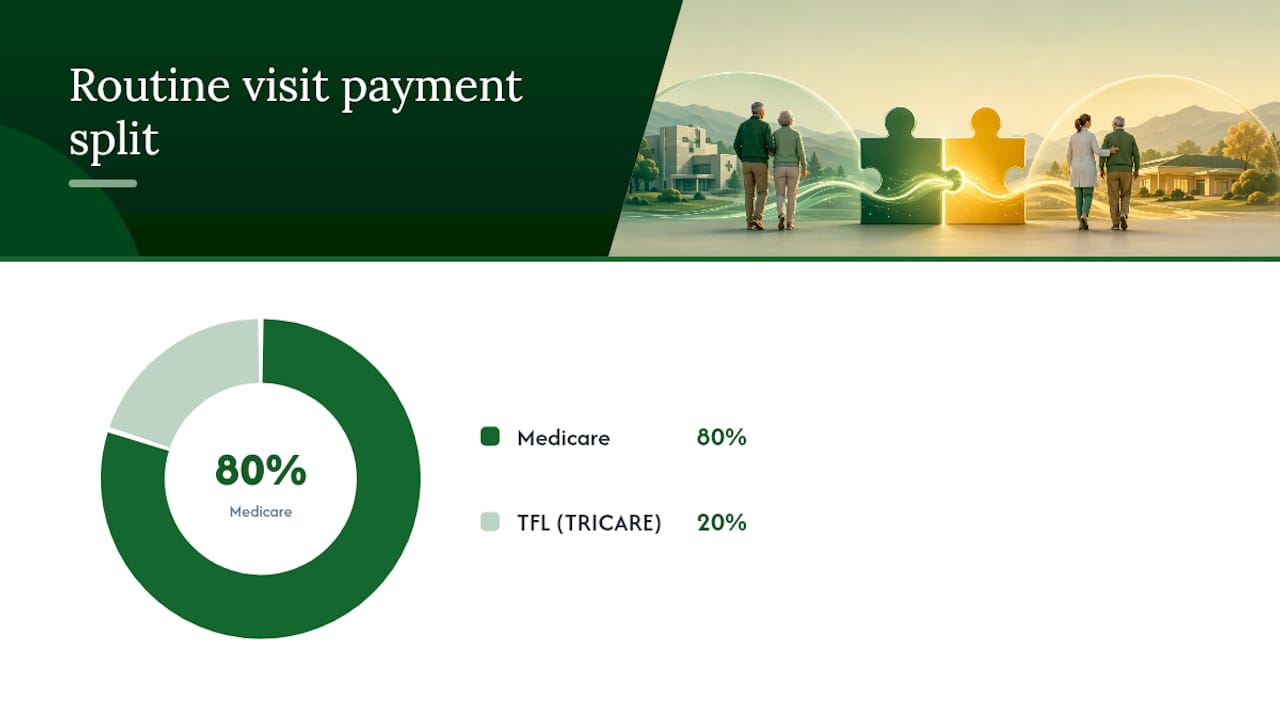
- Routine primary care visit, Medicare-participating provider: Medicare pays 80%, TFL covers the remaining 20% coinsurance. You pay $0.
- Hospital stay exceeding Medicare’s covered days: TFL may extend coverage TRICARE normally provides, reducing what would otherwise be a large personal bill.
- Service Medicare doesn’t cover but TRICARE does: TRICARE pays as primary, and you’re responsible only for any TRICARE cost-share.
Claims don’t always flow automatically, especially with providers who don’t participate in electronic crossover. In those cases, you may need to file a paper claim directly with TRICARE’s claims processor. Keep every explanation of benefits (EOB) from Medicare, along with receipts and provider statements, for at least a year. If a claim stalls for more than 30 days, that’s your cue to call and check on it rather than assume it’s being handled.
Pro Tip: Photograph or scan every Medicare Summary Notice the moment it arrives. If a TFL claim gets questioned months later, having the original EOB on hand saves weeks of back-and-forth with the claims processor.
Do You Need Medicare Advantage or Part D With TRICARE For Life?
Short answer: usually not, and here’s why. Medicare Advantage (Part C) plans replace Original Medicare with a private network, which can conflict with how TFL coordinates payments. Because TFL already functions as robust, nationwide secondary coverage, layering an Advantage plan on top often adds network restrictions and referral hurdles that retirees didn’t have with Original Medicare plus TFL.
Part D works similarly. TRICARE’s pharmacy program, run through Express Scripts, already provides credible drug coverage, so most retirees don’t need to add Part D.
- Original Medicare plus TFL gives you the widest provider access with no network restrictions.
- Advantage plans can make sense if you want extra perks like dental or vision bundled in, but weigh that against losing flexibility.
- Consider Part D only if your specific medications aren’t well covered under TRICARE’s formulary, which is uncommon but not impossible.
- If you travel extensively or split time between states, Original Medicare plus TFL avoids the network headaches Advantage plans can create.
What Changes If You Live Overseas or Use VA Care?
Medicare’s coverage stops at the U.S. border. If you’re living overseas, TRICARE often becomes your primary payer instead of secondary, since Medicare simply doesn’t pay for foreign care.
VA facilities complicate the usual order of payment. Medicare generally doesn’t pay for VA care, and TRICARE’s coordination with VA providers works differently than with civilian Medicare providers, sometimes leaving you with costs you wouldn’t face at a Medicare-participating civilian office.
- Confirm with a provider whether they accept Medicare assignment before assuming your usual cost-sharing applies.
- If you carry other health insurance (OHI) through an employer or a spouse’s plan, that OHI typically pays before Medicare and TRICARE, changing the whole payment order.
Your 7-Step Checklist Before and After Turning 65
Getting this right isn’t complicated, but the sequence matters more than people expect.
- Mark your Initial Enrollment Period on the calendar, three months before your birthday month.
- Confirm whether you qualify for premium-free Part A based on your or your spouse’s work history.
- Enroll in Part B through Social Security even if you’re tempted to delay.
- Update DEERS with your Medicare information the same week your card arrives.
- Double-check that your military ID and Medicare card both reflect current, accurate information.
- Review your prescription needs against TRICARE’s pharmacy formulary before assuming you need Part D.
- Save every claims processor contact number in case a bill needs follow-up.
Pro Tip: Call DEERS the month before your 65th birthday, not the week of. Processing delays are common, and a one-week cushion has saved plenty of retirees from a frustrating gap in coverage.
How Green Insurance Agency Helps You Coordinate Medicare and TRICARE
Sorting through Part B timing, Advantage tradeoffs, and pharmacy coordination is exactly where Greenins’s certified Medicare Insurance Planners® step in. With over 625 client reviews and recognition as a top agency in Clay County, Florida, Greenins has guided retirees through this same transition many times over.
- Turning-65 consultations that map your specific enrollment timeline
- Guidance on whether Part B timing puts you at risk of a penalty
- Help evaluating whether Advantage or Part D genuinely fits your situation
- Support if a TFL claim gets stuck or denied
What Retirees Consistently Get Wrong About This Transition
The biggest misconception is thinking TRICARE For Life is optional or something to “activate.” It isn’t. It’s automatic, and treating it as an afterthought is exactly how people end up with enrollment gaps. The retirees who struggle most aren’t the ones with complicated medical needs. They’re the ones who assumed Medicare enrollment could wait until things “settled down” after 65.
My practical advice: verify your DEERS record the month before your birthday, not after. That single habit prevents more billing headaches than anything else I’ve seen discussed with retirees navigating this system.
— Zach
Schedule a Free Medicare Consultation With Greenins
Greenins offers something a call center or generic online quote tool can’t: a real conversation with a certified Medicare Insurance Planner® who walks through your specific timeline, your prescription needs, and whether Advantage or Part D actually makes sense for your situation, instead of a one-size-fits-all recommendation.

A consultation covers your Part B enrollment timing, a side-by-side look at whether Medicare Advantage adds value or just adds friction, and a check of your prescriptions against TRICARE’s pharmacy formulary. Bring your Medicare card, military ID, and a list of current medications. These consultations are free, and Greenins is compensated by carrier commissions when you enroll in a plan, never by charging you directly. Visit Greenins to schedule your free consultation and get a clear answer on your enrollment timeline before your window closes.