
You can switch Medigap plans anytime, but insurers only have to accept you without health questions during specific windows. The one-time, six-month Medigap Open Enrollment Period is your strongest right. Outside it, guaranteed issue rights and the Medicare Advantage trial right cover most other cases, but everything else runs through medical underwriting. Never cancel your current policy until the new one is confirmed in writing, and check Medicare.gov, your State Health Insurance Assistance Program (SHIP), and your state insurance department before you act.
TL;DR:
- The six-month Medigap open enrollment period begins when you turn 65 and enroll in Medicare Part B, providing guaranteed issue rights regardless of health.
- You have 63 days from a qualifying event, such as insurer bankruptcy or coverage loss, to apply for guaranteed issue Medigap coverage without underwriting.
- Outside protected windows, insurers may require medical underwriting, leading to higher premiums, coverage exclusions, or outright denials, which vary by company and state.
- The Medicare Advantage trial right allows a 12-month period to switch back to Medigap with guaranteed issue coverage if you originally enrolled in Medicare Advantage.
- Certain states, like California and Oregon, offer additional protections such as birthday rules or year-round guaranteed issue, beyond federal rules.
Table of Contents
- What Is the Medigap Open Enrollment Period, and When Does It Start?
- What Triggers Guaranteed Issue Rights When Switching Medigap Plans?
- What Happens if You Switch Outside a Protected Window?
- How Does the Medicare Advantage Trial Right Affect Your Medigap Options?
- Do Some States Offer Extra Protections When Changing Medigap Coverage?
- How Do You Switch Medigap Plans Step by Step?
- What Mistakes Cost Beneficiaries the Most When Switching Medigap Plans?
- How Green Insurance Agency Helps You Navigate a Medigap Switch
- Get a Free Medigap Switch Review From Green Insurance Agency
- Where to Verify Medigap Switching Rules Yourself
- Sources
What Is the Medigap Open Enrollment Period, and When Does It Start?
Your Medigap Open Enrollment Period starts the month you turn 65 and are enrolled in Medicare Part B. It lasts for a limited period and happens once in your lifetime, not annually. Medicare confirms that during this window, insurers cannot deny you a policy or charge more based on your health.
That protection is significant because it flips the usual rules of insurance:
- Insurers must sell you any Medigap policy they offer, regardless of your medical history.
- They cannot charge you a higher premium because of a past or current condition.
- They cannot impose a waiting period for preexisting conditions if you had prior creditable coverage.
- You do not need to answer health questions on your application.
If you already own a Medigap policy and your six month window has closed, switching to a different plan later generally means underwriting applies again, unless a guaranteed issue event or state rule gives you another path in. That’s why timing this decision matters more than almost any other Medicare choice you’ll make.
What Triggers Guaranteed Issue Rights When Switching Medigap Plans?
Guaranteed issue rights let you buy a Medigap policy without medical underwriting when specific events happen, even outside your initial enrollment window. NCOA outlines the events that typically qualify, along with the tight deadlines attached to each one.
- Your insurer stops offering your current plan or goes bankrupt, leaving you without coverage.
- You move out of your plan’s service area.
- You lose employer or union coverage that was paying secondary to Medicare.
- You joined a Medicare Advantage plan when you first became eligible and disenroll within 12 months (the trial right).
- Your Medigap insurer misled you or violated marketing rules.
Most of these situations give you 63 days from the date your coverage ends to apply for guaranteed issue. Miss that window, and you’re back to standard underwriting. Gather your termination notice, proof of prior coverage dates, and any letters from your old insurer or employer before you apply. Documentation gaps are the most common reason applications get delayed.
What Happens if You Switch Outside a Protected Window?
Outside a protected window, insurers can put you through medical underwriting, meaning they review your health history before deciding whether to accept you and at what price. According to Medicare Interactive, outcomes vary: an insurer might accept you at standard rates, charge you more, exclude coverage for a specific condition, or deny the application outright.
Some states allow a waiting period of up to six months for preexisting conditions, though prior continuous coverage often shortens or eliminates that wait. Underwriting standards differ by company, which means a denial from one insurer doesn’t guarantee a denial everywhere.
Pro Tip: Get underwriting decisions in writing before you cancel anything. If one carrier turns you down, apply with two or three others; their risk tolerance and health questionnaires aren’t identical.
- Request quotes from multiple insurers rather than assuming your current carrier is your only option.
- Ask each company directly how it treats your specific conditions.
- Keep your existing Medigap policy active until a new one is approved and effective.
How Does the Medicare Advantage Trial Right Affect Your Medigap Options?
If you enroll in a Medicare Advantage plan when you first become eligible for Medicare and decide it isn’t right for you, the Medicare Advantage trial right gives you 12 months to switch back to Original Medicare with guaranteed issue protection for a Medigap policy. Kiplinger notes this trial right also covers certain beneficiaries who dropped a Medigap policy to try Medicare Advantage for the first time.
Outside that trial period, moving from Medicare Advantage back to Medigap typically requires underwriting, and approval isn’t guaranteed. Industry coverage from 247wallst frames this bluntly: switching to Medicare Advantage is easy, but switching back can be close to impossible for beneficiaries with health issues.
- If you’re testing Medicare Advantage, mark your 12-month trial deadline on a calendar the day you enroll.
- Don’t let your Medigap policy lapse for good until you’re confident in your Medicare Advantage decision.
Do Some States Offer Extra Protections When Changing Medigap Coverage?
Federal rules set the floor, not the ceiling. A number of states go further, according to MedicareCoverGuide, which tracks these variations closely.
- California and Oregon offer a “birthday rule” letting you switch to an equal or lesser plan within a set window around your birthday each year, no health questions asked.
- Connecticut, Massachusetts, and New York require continuous or year-round guaranteed issue, meaning insurers must accept applicants regardless of health status at any time.
- Washington and Maine have their own variations on guaranteed acceptance that go beyond the federal minimum.
Rules change and eligibility details get specific, so confirm current requirements with your SHIP counselor or your state insurance department before assuming a state protection applies to you.
How Do You Switch Medigap Plans Step by Step?
Switching to a new Medigap plan safely comes down to sequence. Do these out of order, and you risk a coverage gap or a denied application.
- Confirm your protected status: open enrollment, a guaranteed issue event, or an active MA trial right, and note your exact deadline.
- Collect documentation: termination letters, proof of prior coverage, and dates tied to your qualifying event.
- Compare plans by standardized letter benefits and price across insurers, since Plan G from one company covers the same benefits as Plan G from another.
- Submit your application and wait for written acceptance before making any other moves.
- Use your 30-day free-look period and keep your old policy active until the new one is effective.
- If denied, ask for the reason in writing and apply with a different insurer or contact your state insurance department.
Pro Tip: Overlap your old and new Medigap premiums for one month on purpose. That extra payment is cheap insurance against a mid-switch coverage gap.
What Mistakes Cost Beneficiaries the Most When Switching Medigap Plans?
Never cancel your current Medigap policy until the replacement is confirmed active in writing. Use the Medicare Plan Finder on Medicare.gov alongside your SHIP counselor to compare insurers by plan letter and premium, since benefits are standardized but prices vary widely.
- Don’t confuse the fall Medicare Annual Enrollment Period (October 15 to December 7) for Medicare Advantage and Part D with Medigap switching rules; it grants no guaranteed issue rights for Medigap.
- If you’re under 65 with a disability or receiving Medicaid, verify special state rules before applying, since standard guaranteed issue timelines don’t always apply the same way.
How Green Insurance Agency Helps You Navigate a Medigap Switch
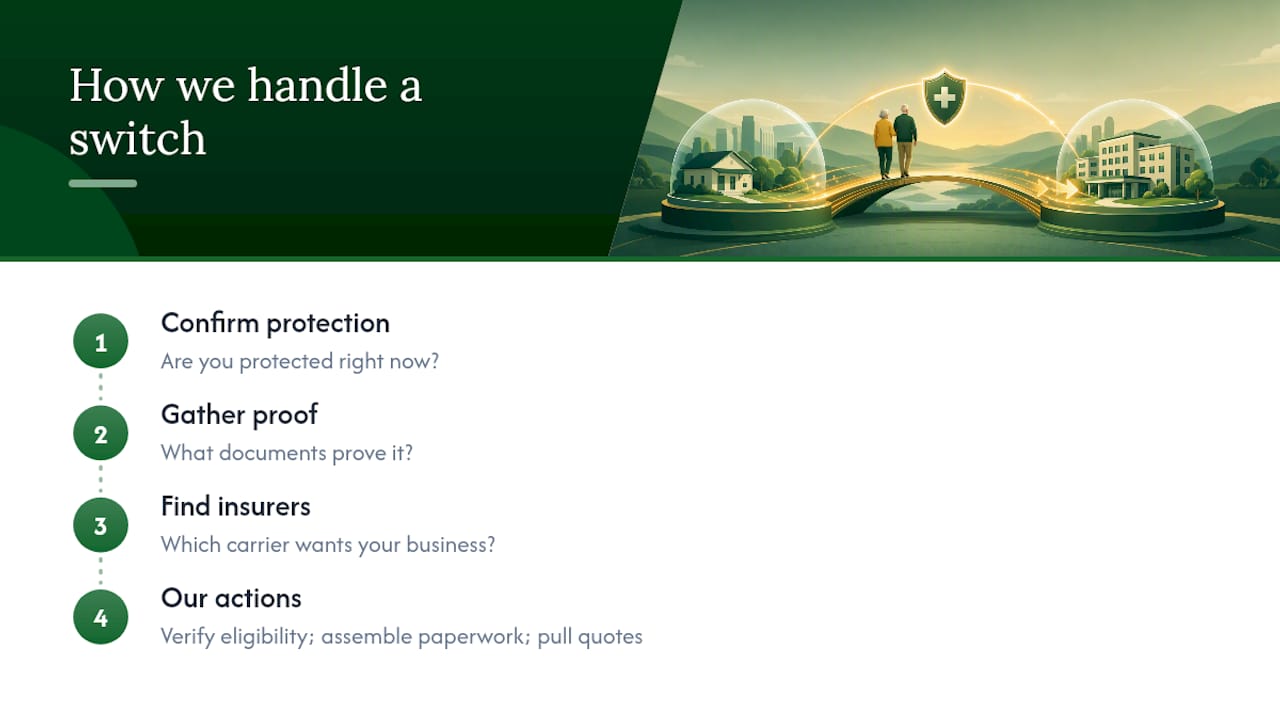
Every switch we’ve walked clients through comes down to the same three questions: are you protected right now, what documents prove it, and which insurer actually wants your business. Our certified Medicare Insurance Planners® verify guaranteed issue eligibility, help assemble the paperwork insurers demand, and pull quotes across multiple carriers instead of pushing one option.
If you want a second set of eyes on your situation, Green Insurance Agency’s consultation page is the place to start.
— Zach
Get a Free Medigap Switch Review From Green Insurance Agency
Greenins is the alternative to sorting through insurer paperwork and underwriting rules on your own. Instead of guessing whether your birthday falls inside a state protection window or whether your qualifying event still counts, a certified Medicare Insurance Planner® checks your guaranteed issue status, reviews your state’s specific rules, and shops multiple carriers side by side for you.

The consultation is free, and it doesn’t end once you’re enrolled. Green Insurance Agency continues supporting clients with annual coverage reviews and claims questions long after the switch is done. If you’re weighing a change to your Medigap coverage, schedule a free consultation and get a straight answer on whether you’re protected before you apply anywhere.
Where to Verify Medigap Switching Rules Yourself
Before you submit any application, confirm the details directly with these sources rather than relying on secondhand summaries.
- Medicare.gov’s Medigap policy pages cover switching rules, the free-look period, and how to compare plan benefits.
- Your local SHIP office offers free, unbiased counseling on guaranteed issue events and state-specific rights.
- Your state insurance department can confirm birthday rules, continuous-issue requirements, and deadlines that apply where you live.
- CMS (Centers for Medicare & Medicaid Services) publishes the federal regulations underlying all Medigap guaranteed issue protections.
Save every document tied to your qualifying event, and verify your deadline the same week your coverage change occurs.
Sources
- Can I change my Medigap policy? | Medicare
- How to Change Your Medigap Policy: A Guide | NCOA
- The Rules for Making a Medigap Switch | Kiplinger
- Medigap purchasing details, enrollment periods, guaranteed issue and more | Medicare Interactive
- Switching Medigap Plans - Best Comprehensive Guide (2026) | MedicareCoverGuide