
Medicare Hearing Aid Coverage in 2026, U.S. Planner's Billing Checklist
Short answer: Original Medicare does not cover hearing aids. Diagnostic hearing and balance exams may be covered when a doctor orders them for a medical reason, but the devices themselves, and the visits to fit them, are excluded by law. Most people end up leaning on Medicare Advantage, VA benefits, state Medicaid, HSA or FSA dollars, or paying out-of-pocket for the hardware.
TL;DR:
- Medicare Advantage plans may offer some hearing benefits, but they often come with network restrictions, vendor limits, and prior authorization requirements.
- Original Medicare does not cover hearing aids or fittings, but diagnostic exams for medical issues are typically covered if ordered by a doctor.
- Veterans’ benefits, Medicaid, HSA or FSA funds, and OTC hearing aids are alternative options that can help offset hearing loss costs outside Medicare.
- The proposed Medicare Hearing Aid Coverage Act aims to remove the statutory exclusion, but it remains unpassed and unenacted into law.
- Proper documentation, provider network verification, and itemized billing are essential for maximizing insurance claims and minimizing out-of-pocket expenses.
Table of Contents
- What Does Original Medicare Actually Cover?
- How Do Medicare Advantage Plans Handle Hearing Benefits?
- What Alternatives Exist Outside of Medicare Advantage?
- What Will Hearing Aids Actually Cost You?
- Is Medicare Hearing Aid Coverage Legislation Actually Moving?
- What Should You Ask at Your Next Appointment?
- A Medicare Planner’s Take on Hearing Aid Coverage
- How Green Insurance Agency Can Help You Compare Plans
- Sources
What Does Original Medicare Actually Cover?
The exclusion isn’t a loophole or an oversight. It’s been written into the statutory language since Medicare’s creation in 1965, and Congress hasn’t touched it. Medicare.gov states plainly that hearing aids and hearing aid fittings are “not covered.” That single sentence has shaped how millions of retirees budget for hearing loss.
Here’s the part most people miss: the exclusion applies to the device and the fitting, not to every hearing-related service.
- Diagnostic exams are different. When a physician orders a hearing or balance test to evaluate a medical condition, Part B typically covers it, and you pay 20% of the Medicare-approved amount after meeting your Part B deductible.
- Fitting and device services stay excluded. Prescribing a hearing aid, fitting it, or replacing one, those charges land on you.
- Prosthetic exceptions exist. Cochlear implants and certain bone-anchored devices are treated as surgically implanted prosthetics, and Medicare can cover them when clinical criteria are met.
That last point trips people up constantly. A cochlear implant candidate and someone who needs a standard behind-the-ear hearing aid are dealing with two completely different coverage rules, even though both involve “hearing loss.”
How Do Medicare Advantage Plans Handle Hearing Benefits?
This is where the picture gets messy, mostly because it varies so much from plan to plan. Most Medicare Advantage plans now build in some kind of hearing benefit, but the shape of that benefit changes depending on the carrier, the county, and even the specific plan within the same carrier’s lineup.
Common structures include:
- A fixed dollar allowance toward hearing aids, often renewed every one to three years
- Per-ear caps rather than a combined household benefit
- Network-only vendors, meaning you can’t just walk into any audiologist’s office
- Brand or model restrictions tied to the plan’s contracted supplier
- Prior authorization before the plan will approve the purchase
When comparing plans, look past the headline allowance. Check whether your preferred provider is in-network, what the warranty and trial period look like, whether prior authorization is required, and what your total expected cost is after the allowance runs out.
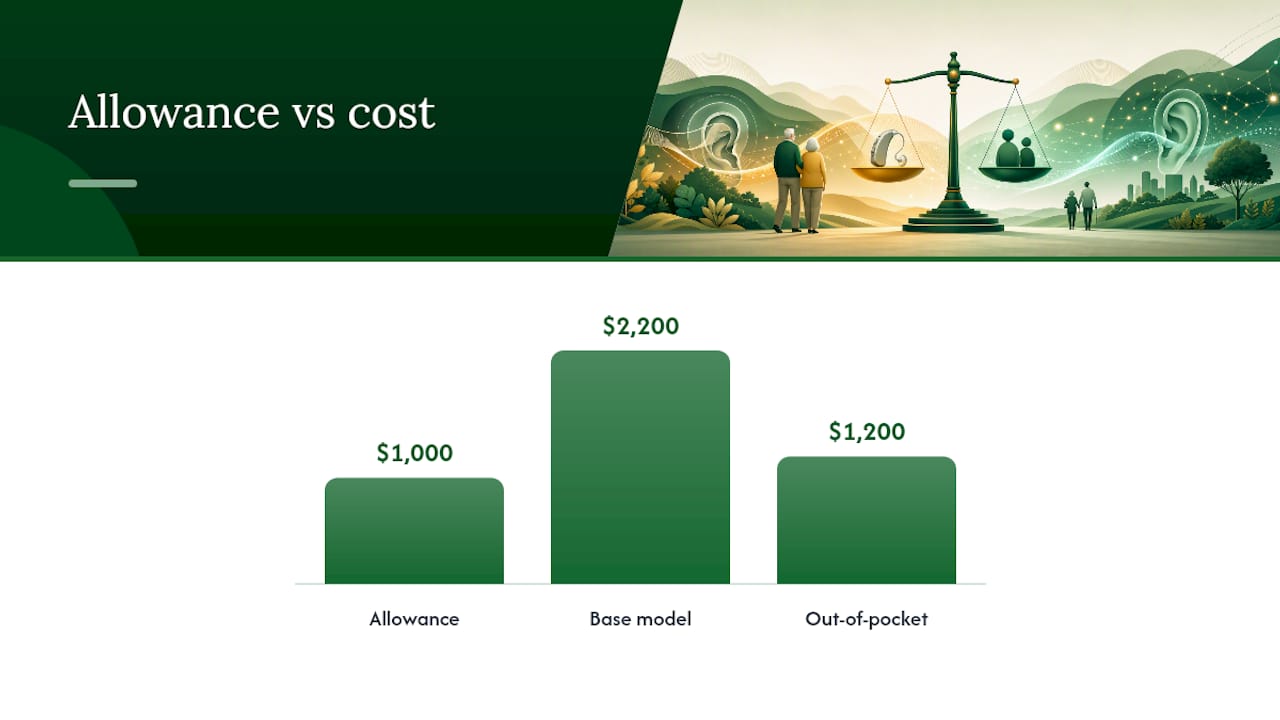
Pro Tip: A $1,000 allowance sounds generous until you learn the plan only works with one vendor whose base model starts at $2,200. Ask for the vendor’s full price list before you enroll, not after.
Plan networks and vendor arrangements often shape your device choice more than the raw dollar amount on the brochure. A generous allowance tied to a limited vendor list can leave you with fewer real options than a smaller allowance on an open network.
What Alternatives Exist Outside of Medicare Advantage?
Original Medicare’s gap doesn’t mean you’re stuck paying full retail. Several other paths exist, and which one fits your circumstances depends heavily on your situation.
- VA benefits. Enrolled veterans generally get comprehensive hearing services and devices, including fittings, repairs, and batteries, often at no cost.
- State Medicaid programs. Coverage varies widely by state, and beneficiaries dual-eligible for Medicare and Medicaid sometimes get help Original Medicare won’t provide.
- HSA, FSA, and HRA funds. Hearing aids, batteries, and related exams qualify as eligible medical expenses under IRS Publication 502, so pre-tax dollars can offset the cost.
- OTC hearing aids. FDA rules allow adults with self-perceived mild to moderate hearing loss to buy hearing aids without a prescription. Original Medicare still excludes them, though some Advantage plans cover OTC devices.
- Cochlear and bone-anchored implants. These remain the exception, covered by Original Medicare as prosthetics when medical criteria are met, unlike standard hearing aids.
What Will Hearing Aids Actually Cost You?
Retail hearing aids commonly run into the thousands of dollars, and Advantage plan allowances often land somewhere between roughly $500 and $2,500 or more per ear, though the exact figure depends entirely on the specific plan you’re enrolled in.
Billing on a single visit can split into two pieces: a diagnostic portion that Part B may cover, and a device or fitting portion billed directly to you. Knowing that distinction changes how you talk to your provider.
- Ask for a written order documenting medical necessity for any diagnostic test.
- Confirm the provider’s network status before your appointment.
- Request an itemized invoice separating diagnostic charges from device charges.
That itemized invoice matters more than most people realize. It’s the difference between a clean insurance claim and a denied one.
Is Medicare Hearing Aid Coverage Legislation Actually Moving?
H.R. 500, the Medicare Hearing Aid Coverage Act, would remove the statutory exclusion entirely and require Medicare to cover hearing aids and related exams for eligible beneficiaries. It’s a real bill with real momentum behind it in certain sessions of Congress.
It has not become law. Until Congress passes it and a president signs it, along with the implementation guidance CMS would need to write, the exclusion stays exactly as it is today.
- If enacted, Original Medicare would likely gain a new coverage pathway for hearing aids.
- Medicare Advantage plans might restructure their existing hearing benefits once a federal floor exists.
- Medigap plans still wouldn’t add hearing aid coverage on their own, since Medigap only covers cost-sharing on services Original Medicare already covers.
- CMS rulemaking after any bill signing would set the real effective dates, so watch agency guidance rather than the bill’s introduction date.
What Should You Ask at Your Next Appointment?
Walking into an audiology appointment or a plan comparison call prepared saves real money. Use this sequence:
- Ask your clinician to document the medical reason for any hearing test, since symptoms like vertigo or sudden asymmetric loss strengthen the case for Part B coverage.
- Ask whether the provider and any recommended hearing aid vendor are in-network for your specific plan.
- Gather existing audiograms, symptom notes, and prior orders before your visit.
- Keep every appeals document if a claim gets denied, including the original itemized invoice.
- Contact your State Health Insurance Assistance Program (SHIP), a certified Medicare planner, or a VA caseworker if your situation involves multiple coverage sources.
Pro Tip: Before you leave any hearing-related appointment, ask the front desk to split your invoice into diagnostic and device line items. That one request makes appeals and HSA reimbursements far easier later.
A Medicare Planner’s Take on Hearing Aid Coverage
Working through Medicare plans day after day at Green Insurance Agency, the same three mistakes show up repeatedly. People assume Medicare Advantage automatically includes generous hearing benefits, they skip checking network restrictions until after buying a device, and they forget HSA or FSA funds can offset costs their plan won’t touch.
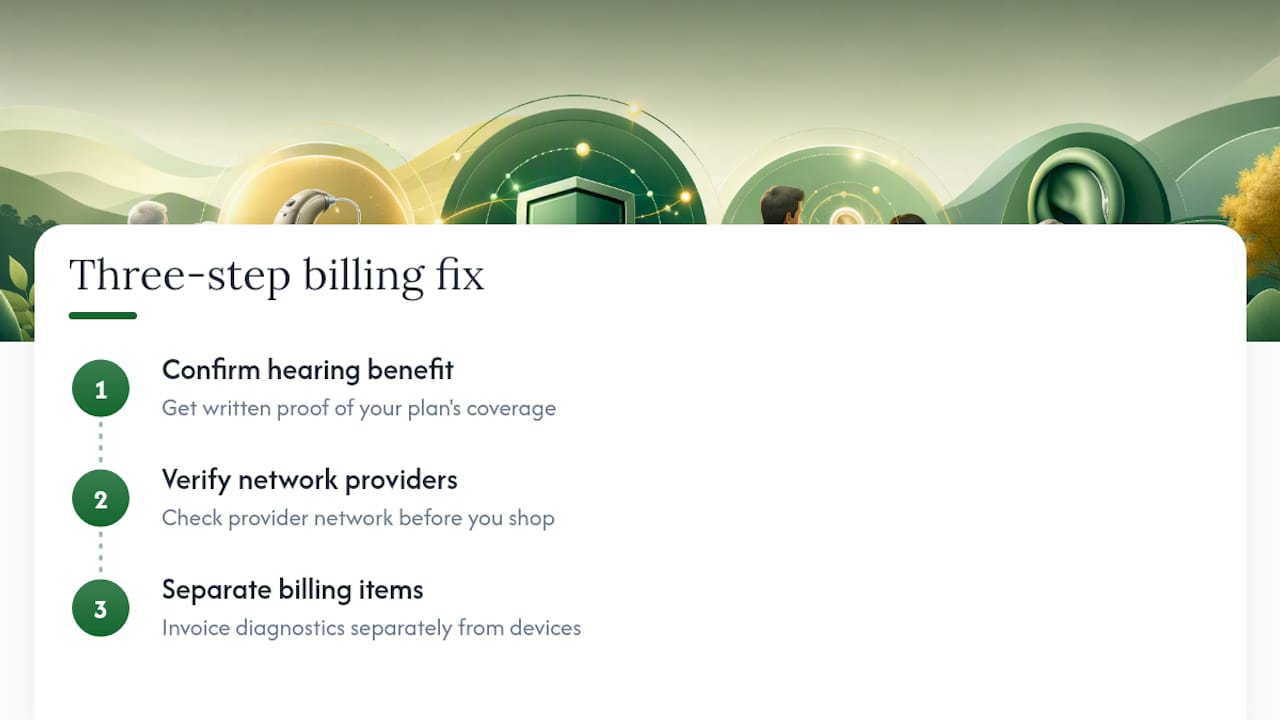
The fix is almost always the same three steps in order: confirm your plan’s actual hearing benefit in writing, verify network providers before you shop, and separate diagnostic from device billing on every invoice. None of this requires waiting on Congress. For anyone juggling Medicare Advantage against Original Medicare plus a supplement, a certified planner can usually spot a mismatch in minutes that would take you weeks to untangle alone.
— Zach
How Green Insurance Agency Can Help You Compare Plans
Sorting through hearing benefit fine print across a dozen Medicare Advantage plans is tedious work, and getting it wrong can mean paying full price for a device your plan was supposed to help cover. Greenins gives you a certified Medicare Insurance Planner® who compares Advantage, Supplement, and Part D options side by side, with specific attention to how each plan handles hearing benefits, network restrictions, and prior authorization.

Beyond initial enrollment, Greenins provides annual plan reviews (useful since hearing benefits and allowances change year to year), claims support if a hearing-related bill gets denied, and ongoing help long after you’ve signed up. The agency’s approach centers on explaining your options rather than rushing you into a sale. If you’re turning 65, reevaluating a current plan, or trying to figure out whether your Advantage plan’s hearing allowance is actually worth using, schedule a consultation with Greenins to walk through your specific situation.